
Step 1
Plug in your zip code and tell us what types of insurance you’re looking for.
Home > Insurance > Home and Auto Insurance > Arizona
Work with a RamseyTrusted® insurance pro. They’ll shop multiple carriers to find you the right home and auto coverage (bundled or separately) at the right price.
Endorsed by Ramsey Solutions | Independent: Shops Multiple Carriers | Arizona Insurance Experts
Reviewed by Ramsey Solutions | Last updated: October 21, 2026
RamseyTrusted pros are independent insurance agents who understand the coverage needs of Arizonans. They’ll review your current coverage, find gaps, shop multiple carriers, and explain your options. All at no cost. Here’s how it works:
Plug in your zip code and tell us what types of insurance you’re looking for.
We’ll connect you with a pro who serves your area. They’ll reach out within 24 hours (or you can give them a call even sooner).
Your pro will review your current policy limits and deductibles to find any gaps in coverage.
Your pro will shop multiple carriers to find you the right coverage. They make the rec. You make the final call.
We vet each one—aka we filter out all the duds. And because our name is attached to them, these pros are held to a higher standard.
Unlike captive agents, independent agents aren’t tied to one insurance company. They can shop multiple companies to find coverage that best fits your needs.
Flash flooding, wildfires and extreme heat can leave you exposed if you don’t have the right kind of coverage. RamseyTrusted insurance pros understand that a one-size-fits-all policy won’t cut it here.
Michael E.
RamseyTrusted Pro in Scottsdale, AZ
“Honestly, the biggest frustration I hear is, ‘Why did my rate go up? I never filed a claim.’ Up north it’s usually a wildfire score. Down in Phoenix, it’s the roof. Neither one is the homeowner’s fault, and neither one gets explained. That’s really the job . . . shop it across everybody and then actually tell people why.”
Bundling your home and auto insurance can often save you money, but it’s not always the best deal. That’s where a RamseyTrusted insurance pro comes in. They’ll shop bundled and separate policies with the same coverage and deductibles to help you find the best fit for your budget. They do the legwork so you have the facts to make the best call for your coverage and your money.
| Bundle With One Carrier | Separate Carriers | |
|---|---|---|
| Price | Often lower through a multi-policy discount | Can be lower if one carrier prices a policy better |
| Coverage | Limited to what one carrier offers | Choose the best fit for each policy |
| Convenience | One renewal date and one point of contact | More renewal dates and contacts |
| Claims | One company handles both policies | A different company handles each policy |
| Renewal Risk | A nonrenewal on one policy can affect the discount on the other | Each policy renews on its own |

Compare the bundle against separate policies with the same limits and deductibles. A discount only matters if the coverage underneath it is the same.
Arizona only requires 25/50/15 in liability coverage: $25,000 per person and $50,000 per accident for injuries, and $15,000 for property damage. The state minimum may keep you legal on the road, but it usually isn’t enough to protect your wallet after a serious accident.
Have a policy with $500,000 in bodily injury coverage and $250,000 in property damage.
Covers your medical or car/property repair bills in an accident with an uninsured or underinsured motorist.
Arizona insurers have to offer windshield coverage with no deductible, but you have to opt in to get it.
Collector cars, tractors, and motorcycles that are at least 25 years old may need special insurance coverage.
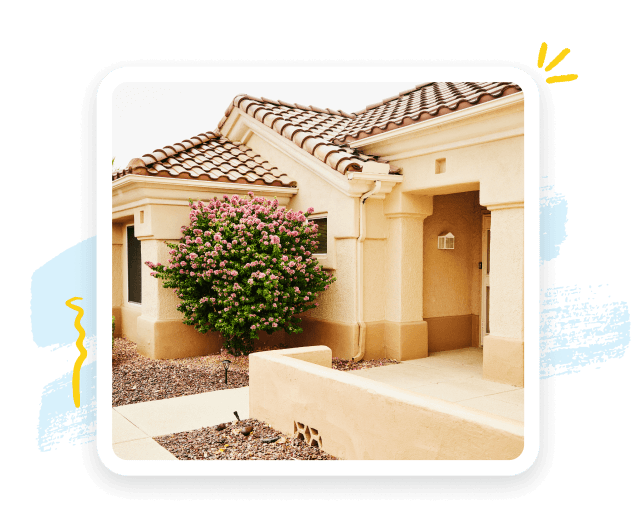
Arizona is full of natural beauty, but it also comes with risks—like wildfires, monsoons, dust storms, extreme heat and flash flooding. And since standard homeowners insurance usually doesn’t cover flood damage, it pays to know what’s covered so you can protect your home with confidence.
Its age, condition and materials can affect your rate and coverage options.
Your dwelling coverage limit should reflect what it would cost to rebuild your home from the ground up—not just what it’s worth today.
Your coverage needs will vary depending on whether you own a condo, second home or mobile home, or rent out your property.
Wildfires are a real threat in northern Arizona. Know your risk and take steps to protect your property.
Extreme weather can damage your property, but not all damage is covered. It depends on your policy and the type of storm.
Standard homeowners policies generally don’t cover flooding and require a separate policy.
Give both policies a checkup at renewal or whenever life changes. An update to one could affect the cost or coverage of the other. Here are good times to review your coverage:
Not ready to talk to a pro? Take the insurance Coverage Checkup. Learn where you might be over or underinsured and get a customized action plan for free.
Get matched with an insurance pro who’ll shop multiple companies for you. No cost. No pressure.
Because of multipolicy discounts, you can often find savings. But to determine the best price, you should compare a bundle against individual policies from separate carriers with the same coverage.
Nope. RamseyTrusted insurance pros are free to work with.
Arizona only requires 25/50/15 in liability coverage: $25,000 per person and $50,000 per accident for injuries, and $15,000 for property damage.
Wind and hail damage are generally covered, subject to meeting your deductible. Flood damage generally isn’t and needs a separate policy. A RamseyTrusted pro can walk you through what makes most sense for you.
Whether you use a RamseyTrusted pro or someone else, to shop policies an agent will need: your current declarations pages, driver’s license info for all drivers, vehicle VINs, home details (year built, roof age, square footage, updates), and claims history.